The fear I hear most often is some version of this: if you file bankruptcy, you will never own a home again — and anything still sitting on title is automatically gone once the discharge arrives.
Neither is true.
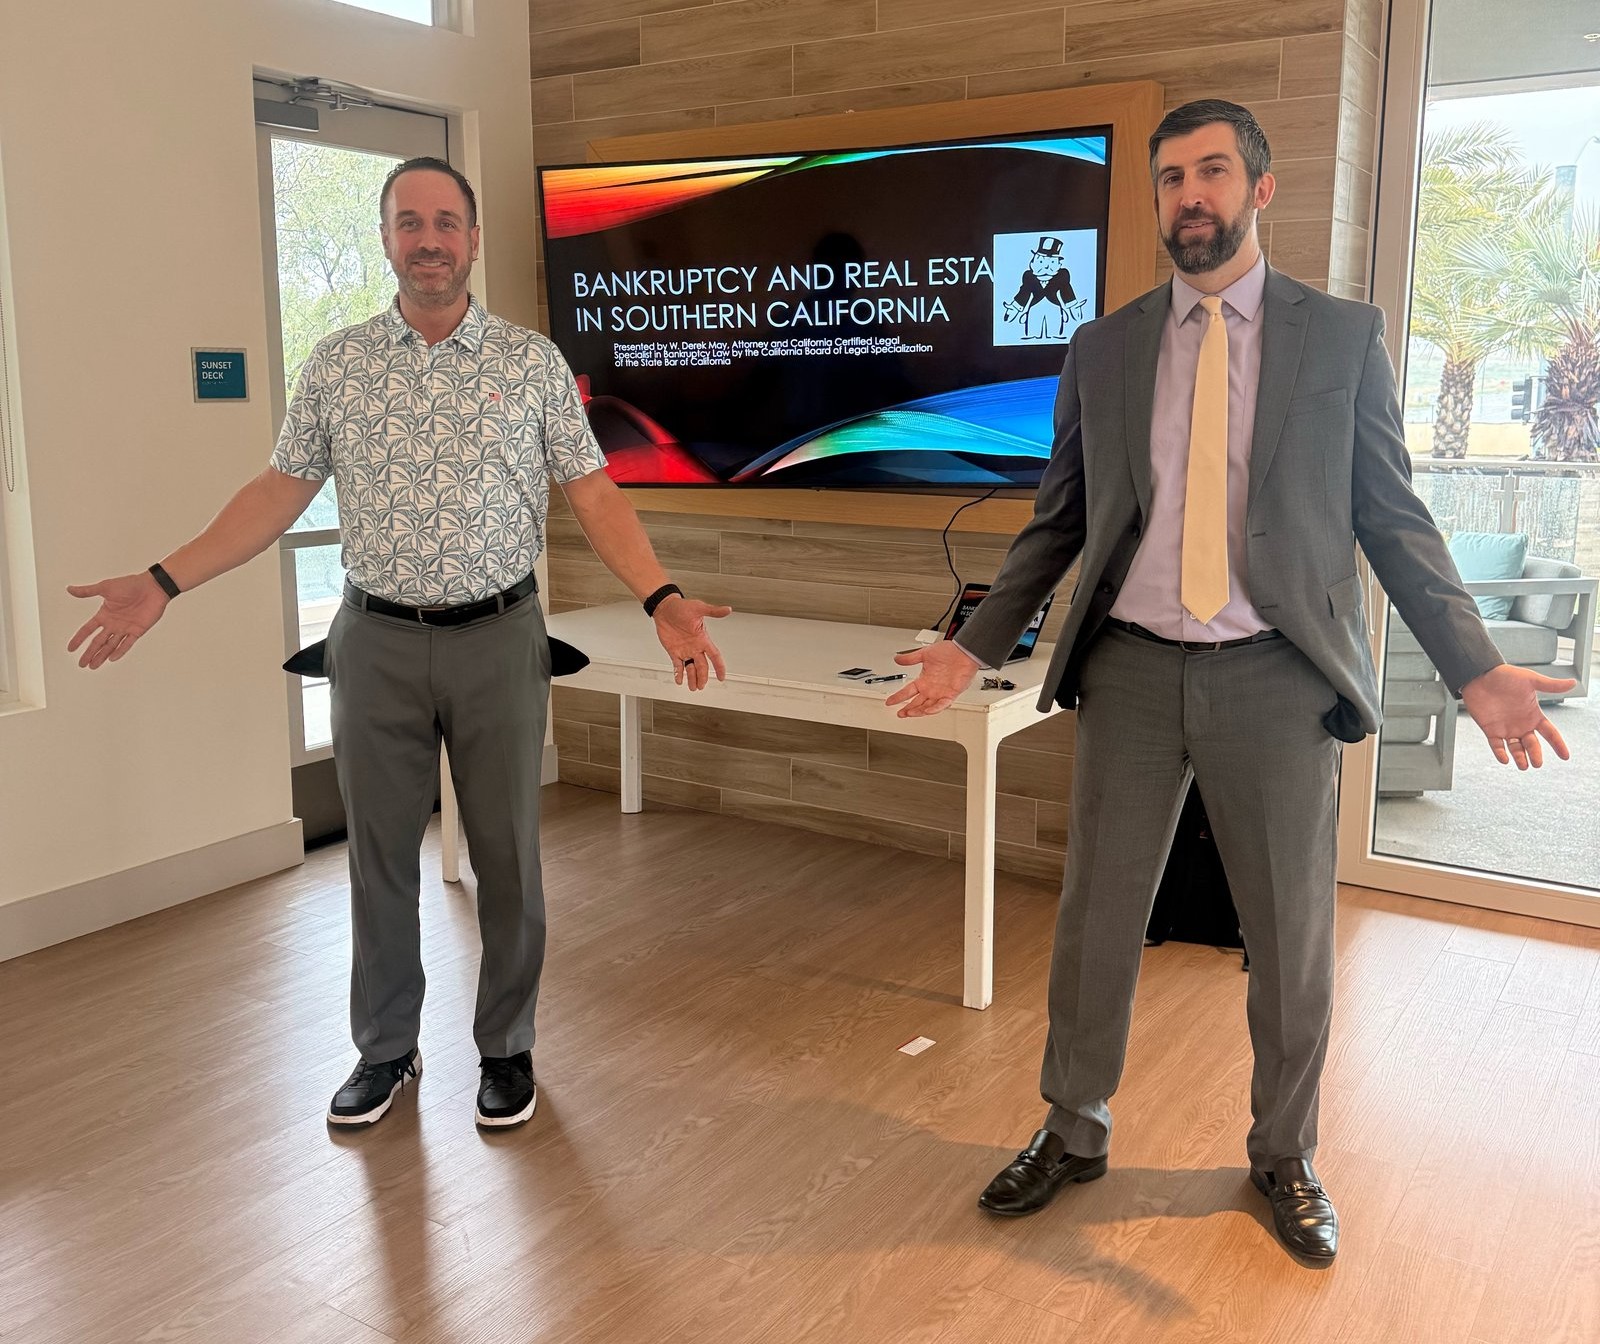
Bankruptcy attorney Derek May joined me at Meetings with Masters on November 19, 2026, in Rancho Cucamonga. He is a California certified legal specialist in bankruptcy law and, as he told the room, likely the only certified specialist in San Bernardino County. He has been practicing bankruptcy for 20 years as of December 2026. What followed was a working session on how consumer bankruptcy actually intersects with a house: the automatic stay, Chapter 7 versus Chapter 13, California’s homestead exemption, why a discharge can still leave judgment liens on title, and what it takes to sell during an open case.
This is the companion to that conversation, drawn from Derek’s slides and the discussion in the room.
Who is calling a bankruptcy attorney right now
Derek has been filing more Chapter 13s to stop foreclosures. Over the summer, he said, he was averaging four or five of those a month. From 2020 to 2022, he had only two or three for that entire stretch.
The calls are not only coming from people who lost a job. A very common story is the household that bought recently, already stretched on the housing payment, and then lost overtime they were counting on. “Anything that happens, it kind of tips it over, and a lot of those people start relying on credit cards to bridge the gap.” Extra cards start covering the minimums on the other cards, “and it snowballs quickly.”
It is not only lower-income households. One couple he described made about $500,000 a year and had about $500,000 in unsecured debt. Their minimum payments were $18,000 a month. Because of debt limits, he could only file for one of them — student loans would have put a joint filing over the cap — and the husband’s Chapter 13 payment dropped to $9,000 a month over five years, with no interest. Then two or three more files like that walked in. “It’s kind of a trend, and these are folks with high income but high expenses.”
For agents, the useful question is not only who is ready to buy or sell. It is also who you know that is stretched right now. That pressure can land on a marriage as much as on a mortgage.
The automatic stay is powerful — if the trustee is actually notified
“The main kind of power that I have as a bankruptcy attorney is the automatic stay,” Derek said. It is created by federal statute, 11 U.S.C. § 362. On a first filing, it is generally triggered the moment the case is filed. It stays collection, repossession, and foreclosure.
Timing still matters. “As long as the bankruptcy is filed before the foreclosure sale takes place, you’re going to stop that sale.” The other half of that sentence is notice. The foreclosure trustee has to know about the filing. The notice of trustee’s sale has a sale number, a phone number, and often a website. Call a person, not only an automated line, and ask exactly where to send the documentation. Derek’s worst-case backup is sending his assistant to the sale itself, or at least creating a record of a fax to the trustee. A stay on paper does not help much if the sale happens because no one was told.
A discharge is the other main reason people file. In a Chapter 7, that typically comes in about four months. In a Chapter 13, it comes after the plan payments are completed — usually three to five years. Derek was careful about the word “wipe out.” “Your debts are still there. You just have legal excuses not to pay them anymore.” That legal excuse is enforced by a discharge injunction, and it does not create the kind of cancellation-of-debt income you can see when you settle a bill outside of bankruptcy.
Not every debt is excused. His usual list included most recent income taxes, sales taxes, and payroll or other “trust taxes” withheld and never turned over — those last ones, he said, are never dischargeable. Student loans come off only if the court finds undue hardship, “a very tough standard to meet.” Ongoing HOA fees keep accruing if you still own the property after the filing. Fraud or willful and malicious conduct is not excused either. “It’s for honest folks, not fraudsters.”
Chapter 7 and Chapter 13 are different tools
Individuals and businesses can file a Chapter 7, but only individuals get a discharge. The debtor’s property becomes property of the bankruptcy estate, and a trustee looks for assets that can be sold to pay creditors. In practice, Derek said, “the vast majority of my cases are no asset cases.” California exemptions, especially the homestead, protect enough value that most people keep their property and discharge the personal liability. That is the “fresh start”: you are not supposed to start over with nothing.
A Chapter 7 can also buy time on a house you cannot keep — often two or three months to arrange a rental or try to sell before the foreclosure starts again. Once the case is over, or the lender gets relief from the stay, the foreclosure can proceed. “The way to save the house and save your equity,” Derek said, “is definitely Chapter 13.”
Chapter 13 is only available to individuals, including self-employed people and realtors filing personally. Instead of a liquidation, the debtor pays disposable income — take-home pay minus reasonable and necessary living expenses — to creditors over 36 to 60 months. Derek flagged an outdated line on his own slide: the CARES Act allowed seven-year plans during COVID. “That was true in COVID times, not anymore.” The maximum is five years.
Plan length depends on whether the household is above or below median income for its size. For a household of one, he used $79,000 as the current median. Below that, a three-year plan is available; above it, the lookback is six months of income, annualized. Even someone who qualifies for 36 months will often stretch mortgage arrears over 60 so the catch-up is actually payable. For commission income, the same six-month lookback applies, and plans can be modified later if income changes.
A Chapter 13 filed mainly to close a sale can be dismissed if that is how the file unfolds. Derek was candid that the U.S. Trustee’s office does not love filings that were never meant to go the distance, and he only does that in the right situation. He also measures success differently than a judge might. A dismissed 13 that still closed the sale is, to him, a success. Of his own Chapter 13s, he estimated maybe one in five go all the way through — and many of the others still did the job, such as catching the mortgage up.
People still tell him that a filing means they will never own a home again. “That’s not true.” His slide listed typical waiting periods for a conventional mortgage of four years after a Chapter 7 and two years after a Chapter 13, and he noted that FHA can be in the neighborhood of two years. Those are general guidelines from the conversation, not a promise about any one loan program.
Filings are up, but not back to pre-COVID
Derek’s “2026 bankruptcy filings through August” slide was for the Central District of California, which covers Los Angeles, Santa Ana, San Bernardino, and Riverside. Through August, the district had 22,471 total cases, up 15.3% from the prior year’s total.
| Chapter 7 | Chapter 11 | Chapter 12 | Chapter 13 | Grand total | |
|---|---|---|---|---|---|
| Opened | 18,626 | 321 | 1 | 3,159 | 22,107 |
| Reopened | 305 | 20 | 0 | 39 | 364 |
| Total | 18,931 | 341 | 1 | 3,198 | 22,471 |
| % change from previous year’s total | 14.8% | 25.8% | 0.0% | 17.8% | 15.3% |
Chapter 7 still makes up the large majority. Chapter 13s are rising faster year over year, which lines up with Derek’s practice, even though he still does far more 7s — on the order of ten Chapter 7s for every Chapter 13. Filings have been creeping up since the historically low COVID years, he said, but they still have not reached 2019 levels. One reason the dip lasted, in his view: fewer creditor lawsuits for a while, because “people thought it was a bad look to sue people during COVID.”
The homestead exemption, and why the county matters
The largest exemption most Californians can claim in bankruptcy is on a primary residence. Derek’s 2026 figures:
- Floor: $371,841 in home equity coverage
- Statutory cap: $743,681
- Los Angeles and Orange Counties: at the cap
- Riverside County: $590,000
- San Bernardino County: $497,000
Those county numbers are adjusted each year from the prior year’s median home price. The January 1 figure is not always final, because the data can lag; Derek said a solid number is usually in place around March.
To claim the exemption in bankruptcy, you do not need a recorded homestead. That is the automatic homestead. A recorded homestead can still help, he said, because it creates a presumption about which property is the homestead — useful if someone owns more than one place. It is for a primary residence, not a rental.
The exemption is not a force field in every situation. If there is substantially more equity than the exemption covers — Derek’s example was $700,000 in equity against a $497,000 exemption — a judgment creditor can try to force a sale. The homeowner would still receive the exempt amount toward another residence; the creditor would take the surplus. The creditors who actually try this, he said, are usually judgment creditors, not the IRS or the state.
He had a client with a 15-year-old deficiency judgment from a car the client had co-signed for a nephew. A small balance had grown into a $70,000 judgment, there was enough equity, and a sale was coming. Bankruptcy was not the right move because of that equity. The client ended up taking a home equity line to pay it. The surprise, Derek said, is how many people do not realize a creditor can sue, take a judgment, lien the house, and garnish wages. They thought nonpayment was “just bad for my credit score.”
Legitimate second and third mortgages are not part of the homestead math. What gets people in trouble is bad pre-bankruptcy “advice” to place a friendly insider lien on the house. If there was no real loan behind it, a trustee can attack that transfer, and the exemption may not be there to save the equity.
One more asset people should not raid first: a qualified retirement account. “I’ll bring this up because this is another kind of sad thing that I see: people will use their retirement and spend it all to make the minimum payments on their debt.” Under California law, a qualified IRA or employer 401(k) can be protected 100%. “If you had a million dollars in your retirement account, you can file for bankruptcy, get a discharge, and still have that for when you retire.” A regular brokerage account is not the same thing, and moving a bank balance into a retirement account on the eve of filing is not either.
The judgment lien that shows up in escrow
This is the part that blows up closings.
A bankruptcy discharge can excuse the personal liability on a debt and still leave a judgment lien sitting against the property. From the title side, that split is everything. When we run a prelim, we are looking at what is attached to the property. A statement of information is what helps us match judgments that came in against a name or Social Security number — or against an entity — to the people who actually own the home. The discharge papers matter. So does a recorded order avoiding the lien. A discharge letter by itself is often not enough.
Derek asks every client about judgments and lawsuits, and he treats lien avoidance as a separate, extra fee, not something automatically bundled into the flat fee for the case. In 2009 and 2010, with so many houses underwater, a lot of people got the discharge and simply left the liens in place. They were not sure they would keep the house.
Those liens can still be addressed later. “We can reopen the case and get an order voiding the lien later. It’s based on the value of the property at the time you filed the bankruptcy.” That is why a historical appraisal is part of the package. Maybe there is a great deal of equity now. If there was not enough equity then, the lien can still be avoided because it impairs the homestead exemption under section 522(f) of the Bankruptcy Code. Derek has gone back as far as ten years. He also had a client this year with eight judgments — about $600,000 in debt — and removed all eight.
Once he has the documents, “it takes about 30 days.” It is not an emergency in the court’s eyes that a ten-year-old judgment is in the way of a closing next week. If a sale is already in escrow, build in that time. Do not assume the original attorney finished this step.
What you generally cannot do later is strip a voluntary second mortgage the same way. That tool is narrower: in a Chapter 13, and only if the junior deed of trust was fully unsecured at filing. Derek did “a ton of those” in 2009 and 2010. “I don’t think I’ve done one for a long time now.”
Judgments also have a life cycle. In California they are typically valid for ten years and can be renewed. Derek noted that a creditor can renew a judgment after a bankruptcy filing to preserve the lien, and that renewal is not a violation of the discharge. If the lien was never avoided, time and a missed renewal are not a plan. Getting the 522(f) order is.
Selling a house while a bankruptcy is open
Yes, a realtor can close a transaction during an active bankruptcy. “They have to get approval of the bankruptcy court.”
It is much harder in a Chapter 7. Derek usually tells clients to wait until the case is over, “because it’s only four months.” To sell during a Chapter 7, the trustee has to abandon the property so it is no longer property of the estate. That is where title and the bankruptcy process can talk past each other. Once the property is abandoned, the court may no longer have jurisdiction to enter the kind of sale-approval order a title company wants to see. “What the title wants, we can’t really give them. That’s the issue.” From the title side, we want a clear court order and a clear map for the proceeds before anyone marks a file as ready to close.
If there is substantial exempt equity and substantial unsecured debt, Derek’s first instinct is often not “just list it and pay everyone.” If the client qualifies for Chapter 7, “it makes much more sense to file for bankruptcy in that situation.” Selling and writing checks to unsecured creditors can leave the household with less than the exemption would have preserved. Exempt proceeds can also be reinvested in another, perhaps more affordable, property within six months, and still kept as exempt.
Another clock: California’s listing-based foreclosure postponement
Bankruptcy is not the only way to buy time to sell. Assembly Bill 2424, codified in California Civil Code § 2924f, lets a homeowner postpone a foreclosure sale with a valid listing, without filing a case.
The requirements are specific:
- Deliver a listing agreement with a California-licensed real estate broker to the foreclosure trustee at least five business days before the scheduled sale. The day before will not work.
- Send it by certified mail or overnight courier with tracking and a signature.
- If those requirements are met, the trustee must postpone the sale for 45 days.
- If you then get a buyer, deliver a fully executed purchase agreement at least five business days before the rescheduled sale and you get another 45 days to close escrow.
“This is not bankruptcy involved. This is just outside of bankruptcy under California law.” Derek’s comparison was honest: “I would say it’s not as strong as a bankruptcy stay, but it is California law.” If a trustee does not follow it, the likely remedy is a wrongful-foreclosure action. A stay violation, by contrast, can go straight to a bankruptcy judge, who can reverse the sale quickly.
That is why the listing statute is a planning tool, not a last-afternoon Hail Mary, and why a bankruptcy filing is sometimes still the only option if the notice window is already gone. In the right file, the two can also work together. We recently had a matter where a foreclosure was days away, a bona fide cash offer went in, money was deposited in escrow, and the sale was stopped. There was also an active bankruptcy, and the court documentation took most of a month. We closed shortly after it arrived.
Why this belongs in the conversation before the prelim comes back
Derek’s practical uses for bankruptcy in a real estate file are straightforward. A Chapter 7 can stop a foreclosure and keep someone in the house for a short window. A Chapter 13 can stop the sale and pay the arrears. Judgment liens can be removed, often years after a case is closed, if the case is reopened and the motion is actually filed. A filing can buy time to sell and preserve equity. Over a longer horizon, clearing unsecured debt can also repair a debt-to-income ratio enough to qualify for a loan again after the waiting period.
The missed step is almost always the one that looks optional on the front end and immovable a week before closing: the lien that was never avoided, the trustee who was never notified, the homestead or retirement account that was never explained, or the sale that needed court approval and did not have it.
If you have a client — or a property — in this situation, call or text Ryan J Orr at 909-447-9266. I can help you think through the title and escrow side with Team Title Guy at Fidelity National Title, including when a deeper look at the public record is worth it, and I can point you to a bankruptcy attorney who actually does this work.
Listen to the full conversation here: After the Discharge: Judgment Liens, Homestead Exemptions, and Selling During Bankruptcy, with Derek May
General information only, not legal, tax, or lending advice. Talk with a bankruptcy attorney and, when a loan is part of the plan, a licensed loan officer about your specific facts. Waiting periods, exemption amounts, and filing figures are as Derek presented them on November 19, 2026, and can change.